 Tyo Susilo
The global semiconductor supply chain is facing a structural reconfiguration as Taiwan Semiconductor Manufacturing Company (TSMC), the world’s largest contract chipmaker, actively searches for equipment motors that do not rely on Chinese rare earth magnets. This proactive measure comes in direct response to tightening export restrictions imposed by Beijing on critical raw materials, a policy shift that threatens to destabilize advanced fabrication facilities worldwide. As geopolitical tensions continue to intersect with high-tech manufacturing, the ripple effects of this material dependency are forcing industry leaders to rethink long-standing supply chain dependencies that have powered the digital economy for decades.
Geopolitical Pressures and Supply Chain Vulnerabilities
At the center of this technological pivot are rare earth elements, a specialized group of 17 chemically similar metallic elements that include neodymium, dysprosium, and praseodymium. These elements are indispensable to modern advanced manufacturing due to their unique magnetic, heat-resistant, and phosphorescent properties. In the semiconductor sector, high-strength permanent magnets crafted from rare earth materials are critical components inside the sophisticated motors that drive semiconductor manufacturing equipment. These motors control the micro-movements, positioning systems, and fluid dynamics required in photolithography, etching, and chemical vapor deposition tools.
China currently commands an overwhelming dominance over the entire global rare earth supply chain. From extraction and complex chemical refining to the mass production of specialized permanent magnets, Beijing holds a near-monopoly. This concentration of power has transformed raw material supply chains into strategic geopolitical leverage. Over recent years, the Chinese government has steadily increased regulatory oversight and implemented targeted export controls on specific rare earth materials, processing technologies, and related manufacturing equipment. While these controls are framed domestically as national security and environmental protection measures, international industry analysts view them as potent tools of economic statecraft amid broader trade frictions with Western nations and their allies.
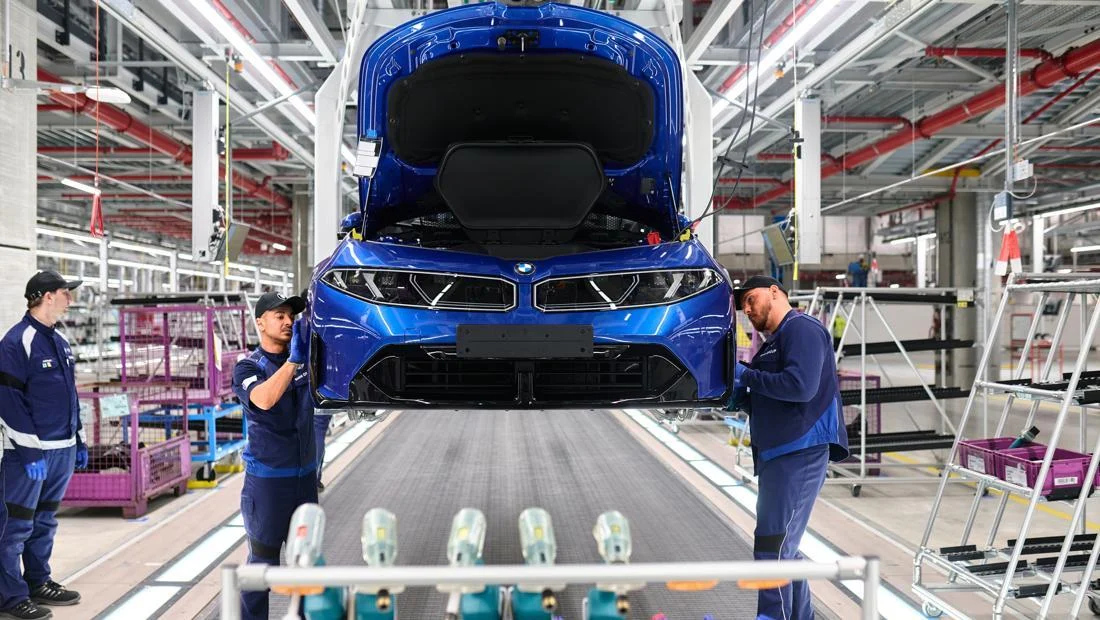
For TSMC, the implications of these export controls extend far beyond basic material sourcing. The operation, maintenance, periodic overhauls, and future expansion of its cutting-edge fabrication plants—known as fabs—rely heavily on uninterrupted access to specialized machinery supplied by global equipment giants such as ASML, Applied Materials, Lam Research, and Tokyo Electron. If Chinese export restrictions eventually encompass the subcomponents, motors, or magnets utilized within these semiconductor manufacturing tools, TSMC faces the distinct prospect of operational bottlenecks. A shortage of replacement motors or maintenance parts could stall multi-billion-dollar production lines, directly threatening the manufacturing output required by top-tier global technology giants.
Chronology of Strategic Risk Mitigation
The urgency surrounding TSMC’s supply chain diversification strategy has accelerated significantly over the past several years, culminating in concrete engineering directives.
The timeline of this unfolding supply chain vulnerability highlights a steady progression toward technological decoupling:

- 2020–2022: China begins tightening regulations on rare earth mining and refining quotas, introducing stricter traceability rules that signal the potential for weaponized export controls. Concurrently, global semiconductor shortages during the COVID-19 pandemic expose deep vulnerabilities in just-in-time manufacturing models.
- Late 2023: Beijing announces formal export restrictions on specific rare earth processing technologies and gallium and germanium, critical materials directly tied to semiconductor fabrication and substrate production. Industry watchdogs warn that magnets could be the next logical category for regulatory tightening.
- Throughout 2024–2025: Geopolitical friction intensifies regarding advanced AI chip exports to China and reciprocal technology curbs. Major fabrication facilities begin conducting comprehensive internal audits to map out single points of failure within their supply ecosystems, identifying heavy reliance on Chinese-origin components in peripheral fab machinery.
- October 22, 2026: Reports emerge confirming that TSMC has officially reached out to its international equipment suppliers to initiate discussions regarding alternative motor technologies. The foundry explicitly asks vendors to research and develop motor configurations that entirely bypass Chinese rare earth magnets.
- Future Outlook (2027–2029): Taiwan’s domestic authorities announce plans to establish pilot production pathways for rare earth processing within a three-year window, targeting self-sufficiency metrics of roughly 50% for local industries. Meanwhile, TSMC continues its exploratory phase with suppliers, though widespread adoption of alternative motor systems remains subject to rigorous engineering validation.
Technical Challenges of Replacing Rare Earth Motors
Redesigning or substituting the motors inside precision semiconductor manufacturing equipment is not a trivial undertaking. Lithography and etching machines operate in hyper-clean, vibration-controlled environments where mechanical tolerances are measured in nanometers. Consequently, transitioning away from neodymium-iron-boron (NdFeB) and other rare earth permanent magnets introduces complex engineering compromises.
TSMC and its equipment suppliers are currently evaluating several primary technological alternatives, each carrying distinct performance trade-offs:
- Induction Motors: These motors operate without permanent magnets, utilizing electromagnetic induction to generate rotor current. While they are robust, cost-effective, and entirely independent of rare earth materials, they traditionally lag behind permanent magnet motors in terms of dynamic response time, energy efficiency at low speeds, and precise positional control—attributes that are vital for advanced fab automation and wafer-handling robotics.
- Switched-Reluctance Motors: Known for their mechanical simplicity, high-temperature tolerance, and absence of permanent magnets, switched-reluctance motors offer high reliability in harsh industrial settings. However, they are historically prone to higher acoustic noise, torque ripple, and complex control algorithm requirements, which can complicate integration into ultra-sensitive semiconductor production tools.
- Ferrite-Based Permanent Magnet Motors: Utilizing strontium or barium ferrite, these motors avoid rare earth elements entirely while retaining a permanent magnet design. While ferrite magnets are abundant and inexpensive, they possess significantly lower magnetic energy products compared to rare earth variants. To achieve comparable torque and power density, ferrite-based motors must be physically larger and heavier, posing a spatial challenge within tightly packed semiconductor manufacturing machinery.
Furthermore, any alternative motor technology must undergo rigorous qualification processes. Semiconductor equipment is certified to perform under stringent uptime, cleanliness (Class 1 cleanroom standards), and precision metrics. Introducing an unproven motor could introduce micro-vibrations or electromagnetic interference that degrades wafer yield—the percentage of functional microchips produced per silicon wafer. Given that a single batch of advanced wafers can be valued in the millions of dollars, equipment reliability remains paramount, slowing down the pace of rapid substitution.
Broader Implications for the Global Technology Ecosystem
The strategic maneuver by TSMC carries profound implications for the entire global semiconductor value chain. As the foundational manufacturer for industry pioneers like Apple, NVIDIA, Advanced Micro Devices (AMD), Qualcomm, and MediaTek, any disruption to TSMC’s operational continuity immediately cascades across consumer electronics, automotive manufacturing, cloud computing, and artificial intelligence infrastructure.
By compelling equipment vendors to engineer non-Chinese rare earth alternatives, TSMC is effectively signaling a broader market shift. Equipment suppliers that successfully diversify their subcomponent sourcing will gain a distinct competitive advantage, securing long-term contracts with major foundries seeking geopolitical insulation. Conversely, suppliers slow to adapt risk losing market share as chipmakers prioritize supply chain resilience over legacy cost efficiencies.
At the national level, Taiwan’s concurrent initiatives to develop domestic rare earth processing capabilities underscore a regional determination to mitigate strategic vulnerabilities. With local authorities aiming to fulfill approximately 50% of domestic demand through pilot refining pipelines over the next three years, the island’s industrial ecosystem is attempting to build localized buffers against trade restrictions. However, because Taiwan lacks extensive natural rare earth ore reserves, these domestic efforts will likely depend on securing raw mineral imports from friendly allied nations such as Australia, the United States, or Vietnam, rather than raw extraction alone.
Ultimately, TSMC’s search for alternative equipment motors illustrates the deepening nexus between industrial manufacturing and international geopolitics. As nations increasingly view critical minerals and high-tech components through a lens of national security, the historical era of frictionless, lowest-cost global sourcing is giving way to a fragmented landscape defined by redundancy, regionalization, and technological self-reliance. For the semiconductor industry, navigating this transition will require unprecedented collaboration between foundries, equipment makers, and material scientists to ensure that the physical machinery powering the digital age remains insulated from geopolitical volatility.