 Tyo Susilo
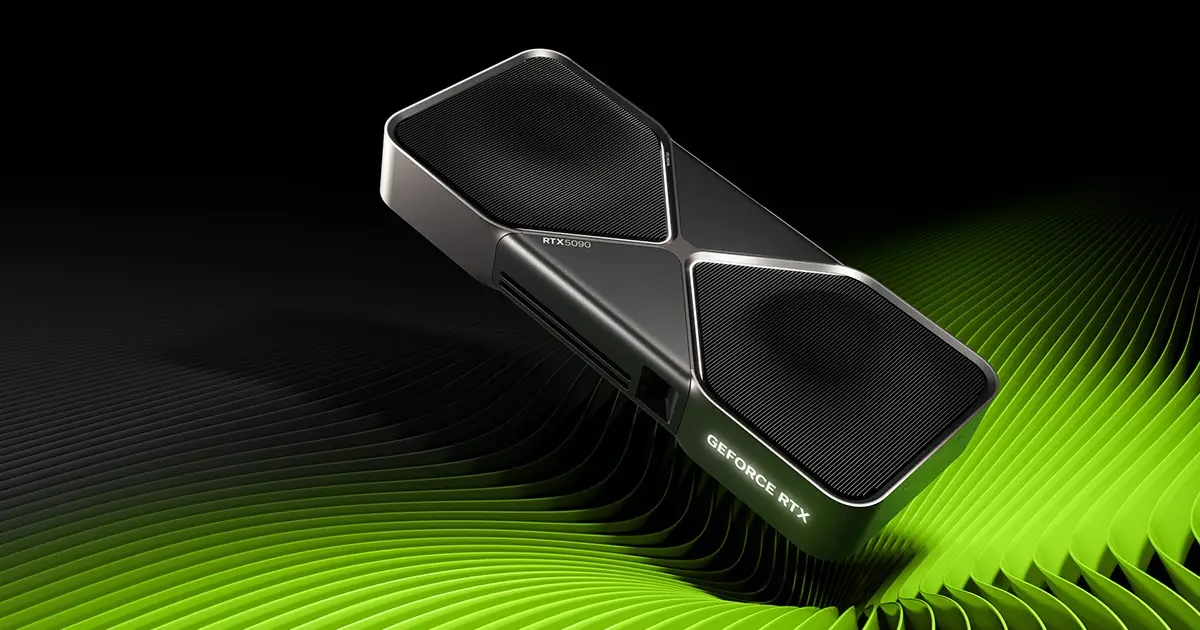
The shifting dynamics of the global semiconductor market continue to influence corporate resource allocation, with recent industry leaks suggesting that multinational technology conglomerate NVIDIA is preparing to pivot its manufacturing priorities away from consumer-grade flagship hardware. According to supply chain whispers originating from prominent hardware insiders, the company is reportedly preparing to wind down the production allocation of the highly sought-after GB202 silicon chips previously designated for the consumer GeForce RTX 5090 graphics card. Instead, available wafer capacity and fabrication resources are expected to be redirected toward enterprise-grade and workstation-focused computing solutions, notably the expanding NVIDIA RTX Pro series.
While the official semiconductor landscape remains highly competitive, the economic incentives driving this strategic realignment are multifaceted, touching upon high-performance computing (HPC) demands, corporate profit margins, and broader global supply chain pressures. As consumer enthusiasts monitor these developments closely, the potential reallocation of crucial GPU architecture highlights the growing dominance of enterprise artificial intelligence and specialized workstation workloads over traditional PC gaming hardware.
Anatomy of a Rumor: The Shift in GB202 Silicon Allocation
The genesis of this recent industry speculation can be traced back to reports from reliable supply chain monitors and hardware leakers, most notably an industry analyst operating under the pseudonym MEGAsizeGPU. According to internal industry channels, NVIDIA is reportedly scaling back its shipment commitments of the flagship GB202 silicon die to board partners for the consumer GeForce RTX 5090 lineup.
The GB202 chip, built upon NVIDIA’s advanced Blackwell architecture, represents the absolute pinnacle of consumer-grade graphical processing power. However, the high manufacturing costs associated with cutting-edge node fabrication, combined with extraordinarily high yields required for enterprise products, have created a compelling financial incentive to prioritize commercial sectors. If the rumors prove accurate, the discontinuation of fresh GB202 chip allocations for the RTX 5090 does not mean an immediate disappearance of the product from retail shelves. Rather, board partners and system integrators are anticipated to exhaust existing inventories of pre-fabricated silicon. Nevertheless, as available stock diminishes, secondary market pricing volatility and component scarcity could introduce significant upward pressure on retail valuations for remaining units.
Strategic Motives: Why Enterprise Takes Precedence Over Gaming
To fully comprehend NVIDIA’s rumored strategic pivot, one must examine the fundamental economics of the modern semiconductor industry. Enterprise solutions, data center accelerators, and high-end professional visualization cards yield significantly higher profit margins compared to consumer-facing gaming hardware.
The enterprise and workstation market—encapsulated by NVIDIA’s professional RTX Pro lineup, such as the recently introduced RTX Pro 5500 powered by the exact same GB202 silicon—commands premium pricing structures. Corporations, research institutions, and cloud service providers are willing to invest heavily in specialized hardware capable of accelerating complex simulations, rendering massive 3D environments, and training deep learning models.
Furthermore, global semiconductor foundries operate under strict capacity constraints. Wafer allocations at advanced fabrication nodes, such as those utilized by TSMC for cutting-end architectures, are fiercely contested. By reallocating a larger share of GB202 wafers to the enterprise sector, NVIDIA can maximize revenue per wafer, optimizing financial performance during a period of unprecedented global demand for artificial intelligence infrastructure and enterprise-level compute engines.
Timeline of the Blackwell Generation and Consumer Impact
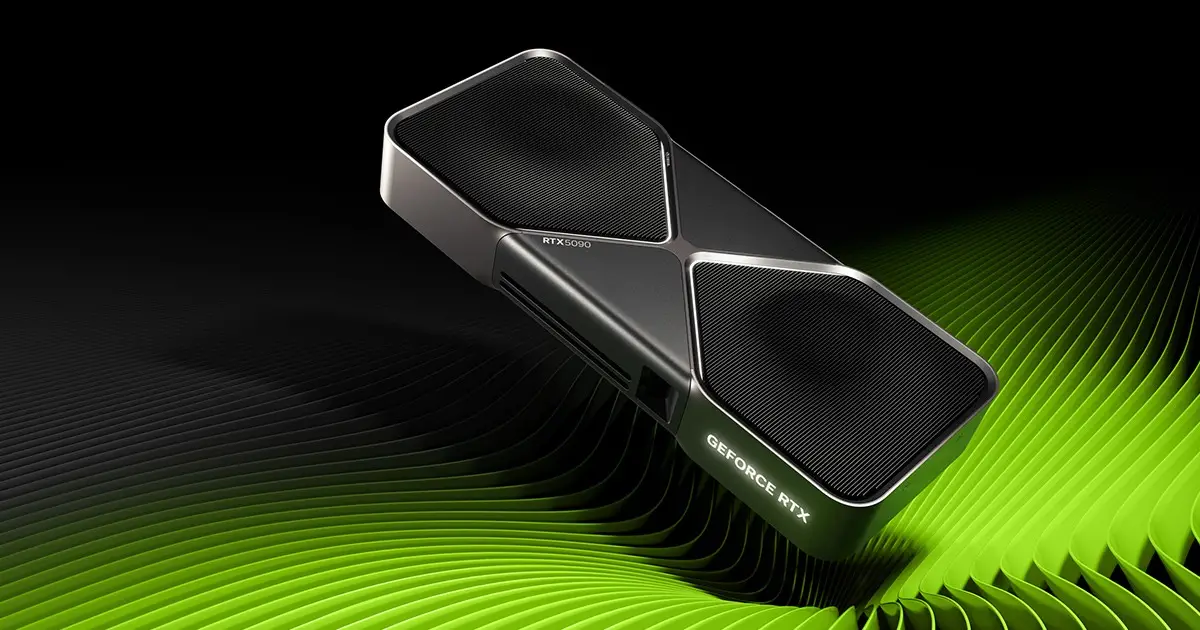
The rollout of NVIDIA’s Blackwell architecture has been one of the most closely watched technology events in recent years. Following initial architectural announcements and subsequent product rollouts, the consumer lineup has faced various logistical hurdles, ranging from production bottlenecks to complex thermal management requirements inherent in high-wattage flagship GPUs.
Historically, flagship consumer cards like the RTX 5090 serve as technological halo products, demonstrating the absolute limits of architectural capability rather than driving core volume sales. However, cutting short the active production life cycle of a premier enthusiast card is an unusual move that underscores the sheer profitability of the enterprise sector. Industry analysts note that while workstation users secure a steady stream of GB202-powered solutions, high-end gamers looking for the absolute maximum performance tier may find their upgrade paths restricted.
Despite rumors suggesting a complete halt in RTX 5090 chip production, questions naturally arise regarding the timeline for subsequent consumer generations. Market observers have debated whether this production shift signals an accelerated timeline for a future GeForce RTX 60 series. However, current consensus among industry forecasters indicates that consumer-facing successors to the Blackwell generation remain on a traditional multi-year cadence, with mass market introductions unlikely to materialize before 2028. Consequently, the void left by a phased-out RTX 5090 may force high-end consumers to pivot toward alternative high-performance options, such as the GeForce RTX 5080 equipped with expanded video memory configurations.
Official Stance and Market Response
As of this writing, NVIDIA has not issued an official press release or corporate statement confirming or denying the rumored cessation of GB202 silicon allocations for the consumer RTX 5090. Corporate policy typically dictates that hardware manufacturers refrain from commenting on leaked supply chain adjustments or unannounced product lifecycle modifications.
Major hardware partners, including prominent original equipment manufacturers (OEMs) and third-party add-in board (AIB) vendors, have similarly remained tight-lipped. However, behind-the-scenes whispers from distributors suggest that component allocation adjustments are indeed being felt across the supply chain. System integrators catering to enterprise clients have reported steadier fulfillment timelines for workstation components, whereas consumer-focused retail channels continue to brace for potential supply constraints and subsequent price adjustments.
Broader Implications for the GPU Landscape
The rumored reallocation of GB202 silicon carries significant structural implications for the broader technology ecosystem. It serves as a clear indicator of a paradigm shift where the gaming segment—historically the foundational bedrock of NVIDIA’s commercial identity—must increasingly share manufacturing resources with the explosive growth of the artificial intelligence and data center sectors.
For the everyday enthusiast, the tightening supply of top-tier consumer silicon highlights the vulnerability of the high-end gaming market to macroeconomic pressures and enterprise demand. As research and development costs for subsequent silicon generations continue to skyrocket, manufacturers are increasingly compelled to chase the highest possible return on investment.
Ultimately, whether these rumors materialize into total production cessation or simply represent a temporary adjustment in regional supply quotas, the message to the consumer market is clear. The boundary between consumer-grade gaming hardware and enterprise-level computational machinery is becoming increasingly porous, with commercial profitability ultimately dictating which products receive priority access to the world’s most advanced silicon fabrication lines.